Are you planning on selling a business UK wide, or perhaps locally here in London? It is a massive and exciting milestone. You have poured late nights, early mornings, weekend shifts, and endless personal energy into building something of real value. You have navigated economic shifts, managed teams, and served your customers with unwavering dedication. But the moment you decide to sell a commercial property, a piece of heavy machinery, or your entire company, a brand new source of stress usually appears on the horizon. That stress is HMRC compliance.
Navigating capital gains tax business assets rules can feel like learning a foreign language while blindfolded. As a hardworking business owner, startup founder, or commercial landlord, you already have enough on your plate. You want to enjoy the financial reward of your hard work. You certainly do not want to be kept awake at night worrying about missed tax deadlines, incorrect asset valuations, or deciphering complex HMRC paperwork.
This comprehensive guide is designed specifically for you. We will break down exactly how the rules apply, what statutory reliefs might be available to you, and how you can prepare your business for a sale. We will replace confusion with absolute clarity so you can move forward with confidence and peace of mind.
What exactly are capital gains tax business assets?
When accountants and HMRC talk about capital gains tax business assets, we are referring to specific items you own and use for your trade that have increased in value since the day you bought them. It is a very common misconception that you pay tax on the total sale price of these items. In reality, you only pay tax on the gain (the profit you have made).
These assets can take many different forms depending on your specific industry. They might be physical, tangible items like commercial property, heavy machinery, specialized manufacturing equipment, or even office furniture. They could also be intangible items. Trademarks, registered designs, patents, and your company’s goodwill all fall strictly under this category.
If you operate as a sole trader or as part of a business partnership, you are personally liable for Capital Gains Tax on the disposal of these items. If you operate as a limited company, the landscape shifts slightly. Your company will pay Corporation Tax on your chargeable gains instead. This distinction is crucial, and it heavily influences your digital record-keeping strategy.
Speaking of records, it is always worth noting HMRC’s ongoing digital push. Most VAT-registered businesses must follow Making Tax Digital (MTD) rules, keeping digital records and using compatible software for their submissions. While MTD currently focuses heavily on VAT and Income Tax, maintaining pristine, organized digital records is undeniably the best way to track your asset purchase costs and sale proceeds accurately over time.
How capital gains tax business assets rules impact your bottom line
Calculating your final tax liability involves a specific mathematical process. You must deduct the original purchase price (alongside any incidental costs of buying, improving, or selling the asset) from the final sale price. You can also deduct your annual Capital Gains Tax allowance if you have not already used it elsewhere in the current tax year.
However, the final bill often depends heavily on the specific tax reliefs you can claim. The UK tax system offers several mechanisms designed to soften the financial blow for entrepreneurs who are selling up, retiring, or reinvesting their funds into new ventures.
Leveraging Business Asset Disposal Relief
Formerly known as Entrepreneurs’ Relief, Business Asset Disposal Relief (BADR) is incredibly valuable for business owners. If you are eligible, it reduces the Capital Gains Tax rate on qualifying assets to just 10%. This preferential rate applies up to a lifetime limit of £1 million in qualifying gains. To qualify for this relief, you usually need to have owned the business or the specific assets for at least two full years leading up to the date of the sale. It is a powerful way to protect the wealth you have built.
Reinvesting with Rollover relief
What if you are not retiring at all? If you are simply upgrading your equipment, buying modern machinery, or moving to a much larger commercial premises, you might be worried about a sudden tax hit stalling your momentum. This is where Rollover relief comes into play. If you sell a qualifying business asset and use all the proceeds to buy a new one, you can delay paying Capital Gains Tax until you eventually sell the new asset. This is a vital, highly effective tool for managing your cash flow during periods of rapid business growth.
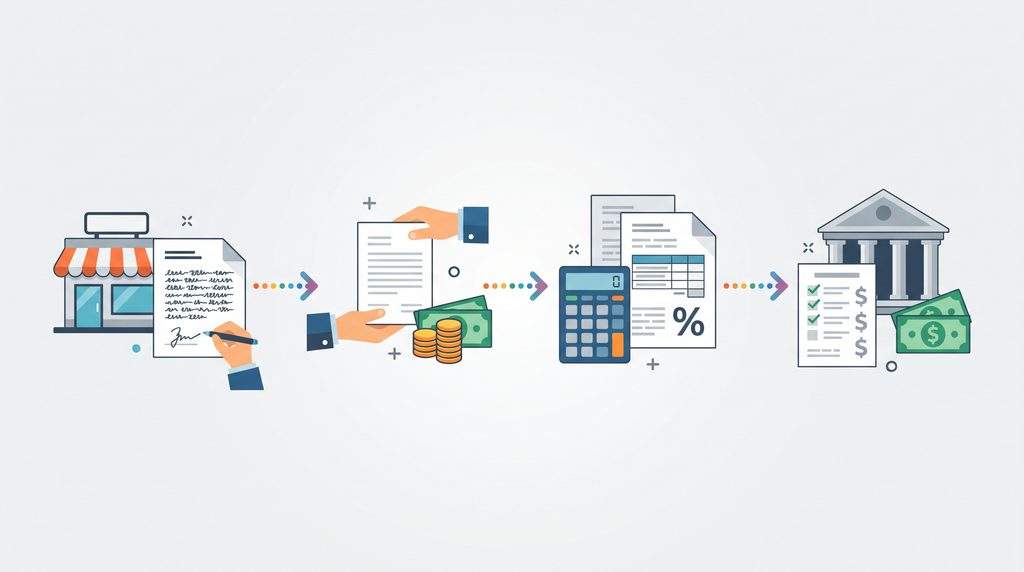
Common errors and record-keeping risks
Managing your tax obligations is rarely straightforward. Even the most careful and well-intentioned business owners can easily slip up when navigating this complex terrain. Here are three common errors and record-keeping risks to watch out for when dealing with your company assets.
1. Misclassifying day-to-day expenses versus capital assets
It is incredibly common to confuse everyday business expenses with capital assets. A routine repair to a manufacturing machine is an expense. Upgrading that machine so it can perform a completely new function is a capital improvement. This difference matters immensely when calculating your base cost for tax purposes.
Furthermore, when dealing with related business costs like business entertainment or company vehicles, remember that the rules are highly nuanced. There are often complex exceptions or partial recovery rules involved depending on how the vehicle is used. You should always seek specific advice before categorizing these complex costs, as getting it wrong can skew your entire asset register and lead to inaccurate tax filings.
2. Missing the strict HMRC reporting deadlines
Time gets away from all of us, especially when running a busy company. But HMRC operates on very strict statutory timelines. If you sell a UK residential property that you used for business (perhaps a buy-to-let investment or a furnished holiday let), you usually have a very narrow window of just 60 days to report and pay the tax due. For most other commercial assets, you typically report the gain much later on your annual Self Assessment tax return.
Be precise with HMRC penalties. If you owe tax and fail to pay on time, late-payment interest begins on day 1. Furthermore, under standard modernized penalty structures, first penalties arise at day 15 and increase at day 30. Keeping on top of your reporting mitigates the risk of these escalating financial costs and helps keep your cash flow predictable.
3. Failing to secure professional, independent valuations
If you sell an asset to a connected person (like a family member, a spouse, or a business partner) or if you give it away as a gift, HMRC requires you to use the open market value for your calculations, not the actual price you received. Many business owners simply guess this value based on a quick internet search. Guessing can lead to significant inaccuracies in your tax return. Using a professional valuer helps improve accuracy and mitigates the risk of HMRC compliance checks.
A step-by-step workflow for capital gains tax business assets
To keep your affairs in order and minimize your stress levels, we highly recommend following a structured, methodical approach. This practical workflow can reduce administrative burden and help you maintain clear oversight of your wealth.
Step 1: Conduct a thorough inventory of your assets
Before you even consider signing a contract or listing items for sale, you must list everything your business owns. Document the exact purchase date, the original cost, and any money spent on significant, value-adding improvements over the years. This forms your legal baseline cost.
Step 2: Track your digital records continuously
Do not wait until the chaotic end of the tax year to find your faded paper receipts. Use cloud accounting software (like Xero or QuickBooks) to tag asset purchases correctly from day one. Engaging a professional bookkeeping service can help you set up a robust, automated system that tracks your asset register seamlessly in the background while you focus on your customers.
Step 3: Determine your current tax allowance status
Check your personal records to see if you have used your Capital Gains Tax allowance for the current tax year. This annual exemption is a strict “use it or lose it” benefit. It cannot be carried forward to future tax years, so planning the timing of your asset disposals around this allowance can be highly beneficial to your overall profit margin.
Step 4: Assess your eligibility for statutory tax reliefs
Before finalizing any sales agreements, review your eligibility for Business Asset Disposal Relief or Rollover relief with a critical eye. The precise timing of your sale, or the structure of your business ownership, can sometimes dictate whether you qualify. Planning ahead is absolutely crucial here.
Step 5: Calculate, review, and report
Calculate the gross gain, carefully apply your eligible allowances and reliefs, and submit the final figures to HMRC via Self Assessment. If it is a property disposal subject to the strict 60-day window, ensure your accountant has all the necessary legal and financial details immediately upon completion of the sale to avoid falling foul of the timelines.
Why outsourcing this task is a smart investment
You started your company to pursue your passion, serve your community, and build a lasting legacy. You did not start a business to become a part-time tax technician. Managing capital gains tax business assets requires a deep, ongoing understanding of constantly changing UK tax legislation.
Outsourcing your tax planning to a dedicated professional is a highly strategic move for any serious business owner. It mitigates the risk of errors in your calculations. It ensures that complex, confusing forms are filed accurately and on time. Most importantly, it frees you up to focus your energy on what you actually do best (running and growing your enterprise).
A qualified professional can look at your holistic financial picture rather than just an isolated transaction. They can advise you on the most tax-efficient time to sell an asset, ensure you are claiming every single relief you are legally entitled to, and structure the disposal to benefit your long-term financial health. While we cannot guarantee that the process will be completely free of paperwork on your end, expert support certainly makes the journey much smoother and significantly less stressful for you and your team.
Your trusted partners at ASK Accountants UK Ltd
At ASK Accountants UK Ltd, we deeply understand the daily pressures you face as a business owner. For over 15 years, we have been proudly helping SMEs, startup founders, and commercial landlords in Wimbledon and across South-West London navigate the complexities of the UK tax system.
We believe in providing proactive, jargon-free advice that makes sense in the real world. We will sit down with you, look at your unique situation, and build a strategy that protects your hard-earned profits. Whether you are selling a single piece of manufacturing equipment, restructuring your property portfolio, or preparing for a major business exit, our dedicated team is here to support you every step of the way.
Are you ready to take the stress out of your tax planning? Let us handle the numbers so you can enjoy the rewards of your business journey.
Call us today on 020 8543 1991, visit our local office at 178 Merton High St, or click here to contact us and book your initial consultation with our expert team.
Frequently Asked Questions about capital gains tax business assets
Do I pay CGT on all capital gains tax business assets? Not always. You only pay tax if the profit (the gain) exceeds your annual Capital Gains Tax allowance. Additionally, if you sell the asset for a loss, you might be able to deduct that allowable loss from other taxable gains you have made in the same tax year, effectively reducing your overall liability.
Does making a mistake with my capital gains tax business assets trigger an HMRC audit? We do not use terms like “trigger an audit,” as HMRC compliance checks can happen for a wide variety of routine reasons. However, poor record-keeping and calculation errors are common risks that can draw unwanted attention. Submitting accurate, professionally prepared returns helps improve accuracy and mitigates the risk of subsequent HMRC inquiries. You can read more about standard compliance checks and official guidelines directly on GOV.UK.
Can I claim relief if I am closing my business entirely? Yes, in many cases. If you close your business and keep the assets personally, you may have to pay tax on their open market value at the exact time of closure. However, Business Asset Disposal Relief often applies when disposing of the whole business or its individual assets upon cessation. This can potentially reduce your tax rate to 10%, provided you meet the strict two-year ownership criteria and other qualifying conditions.